
Workers’ Comp Insurance Audits: What to Expect and How to Prepare
A workers’ comp audit is not an accusation. It is the second half of how the policy is priced. At the start of the year, your premium is based on an estimate of payroll. After the year ends, the insurer looks at what you actually paid, and to whom, for what kind of work. Then it settles up.
The New York State Insurance Fund (NYSIF) even calls it a “payroll verification.” That is a good way to think about it. Below is a timeline of the process, from the months before the audit to the bill or refund that follows.
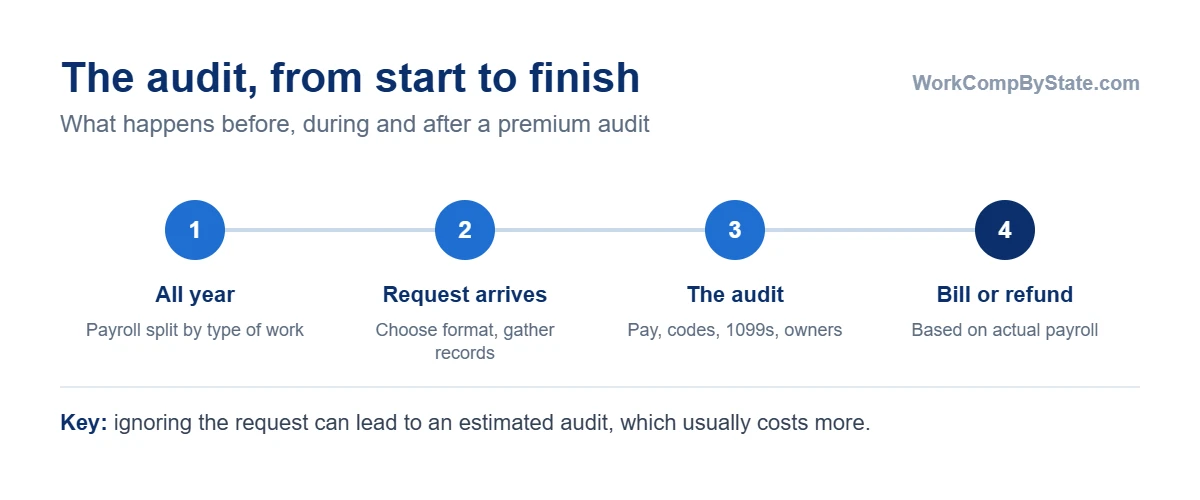
All year long: keep audit-ready records
The easiest audits happen for businesses that never have to rebuild their records. During the policy year:
- Track payroll by type of work. If an employee does both office and field work, your records need to show the split, or the auditor may put all of the pay in the higher class.
- Collect certificates of insurance from every subcontractor before they start, and check the dates cover the whole job. NYSIF states plainly that premium charges for employees of uninsured subcontractors are the policyholder’s responsibility.
- Keep contracts and invoices that describe the work done, especially in construction.
- Tell your carrier about big changes, like a new service line or a jump in headcount, before the audit finds them.
When the request arrives: pick the format and gather documents
Audits are usually done in one of three ways: you complete a self-reporting form, you upload documents for a remote review, or an auditor meets you by video or in person. Smaller, simpler businesses often get the lighter formats. NYSIF, for example, offers onsite audits, virtual audits by videoconference and online document upload.
Here is what NYSIF asks policyholders to have ready. Other insurers ask for similar records.
| Document | Why the auditor wants it |
|---|---|
| Payroll book or payroll register | Gross payroll |
| Payroll tax returns (Form 941 and state returns) | Check the payroll records |
| W-2 and W-3 forms | Verify annual payroll |
| 1099 and 1096 forms | Other payments to workers |
| Cash book, check book or disbursement records | Pay not shown in payroll |
| General ledger | Overview of operations |
| Income tax return (1120, 1065, 1040 or 990) | Confirm figures from the main source |
| Subcontractor certificates of insurance | Verify subs had coverage |
| Contracts, bills and invoices | What work was done, and by whom |
During the audit: what the auditor checks
Expect questions in four areas:
- Total remuneration. NYSIF’s definition goes beyond wages and includes commissions, bonuses, most overtime, holiday and vacation pay, and the value of meals or lodging given as pay.
- Classification. Does each employee’s work match the code on the policy? An auditor may walk the site or ask employees what they do.
- Payments to outside workers. Every 1099 payment is reviewed. If the worker had no coverage of their own and does not meet your state’s contractor test, their pay may be added to your premium.
- Owners and officers. Whether they are included or excluded, and whether the paperwork for any exclusion is in place.
Answer questions plainly and do not guess. If you do not know, say you will check and follow up in writing.
If you ignore it: the estimated audit
Do not let the request sit. NYSIF warns that after missed appointments, insufficient records or no response, it may have to conduct an estimated payroll verification, which can result in premiums higher than a proper verification would produce. Private carriers handle non-response in similar ways, and some may also move to cancel the policy. If you need more time, ask for it.
After the audit: the bill or the refund
The insurer recalculates the premium using actual payroll and the confirmed codes. If the earned premium is higher than what you paid, you get a bill. If lower, you get a refund or credit.
Check how your insurer handles balances. NYSIF charges no interest on audit balances paid in full, but unpaid audit balances are subject to a 1% monthly interest charge.
A worked example (hypothetical numbers)
A painting contractor estimated $150,000 in payroll at a hypothetical rate of $5.00 per $100 and paid a $7,500 premium. The audit finds:
- Actual employee payroll was $170,000.
- A $20,000 payment to an uninsured helper who did not meet the contractor test is added.
Audited payroll: $190,000. Earned premium: $190,000 / 100 x $5.00 = $9,500. The contractor owes $2,000. With a certificate of insurance from the helper, the added $20,000 might never have been on the bill.
If you disagree with the result
Ask for the audit worksheet in writing. Look for wrong codes, payroll counted twice, overtime treated incorrectly, or subcontractors whose certificates you did have. Send corrections with documents to your insurer. If that fails, your agent can escalate, and your state’s insurance regulator or rating bureau usually has a dispute process for classification questions.
A short pre-audit checklist
- Payroll reports for the full policy period, split by job type
- Quarterly payroll tax returns and W-2s
- All 1099s and the matching certificates of insurance
- Job descriptions for each employee
- Owner and officer inclusion or exclusion forms
Related guides
- Certificates of insurance explained
- Pay-as-you-go workers’ comp
- Covering 1099 workers
- How premiums are calculated
Sources
- New York State Insurance Fund, required audit documents
- New York State Insurance Fund, estimated audits
- New York State Insurance Fund, payment plans and audit balances
- New York State Insurance Fund, what affects your premium
Last checked against the sources above on October 2, 2026.