
Workers’ Compensation Insurance Requirements in Georgia
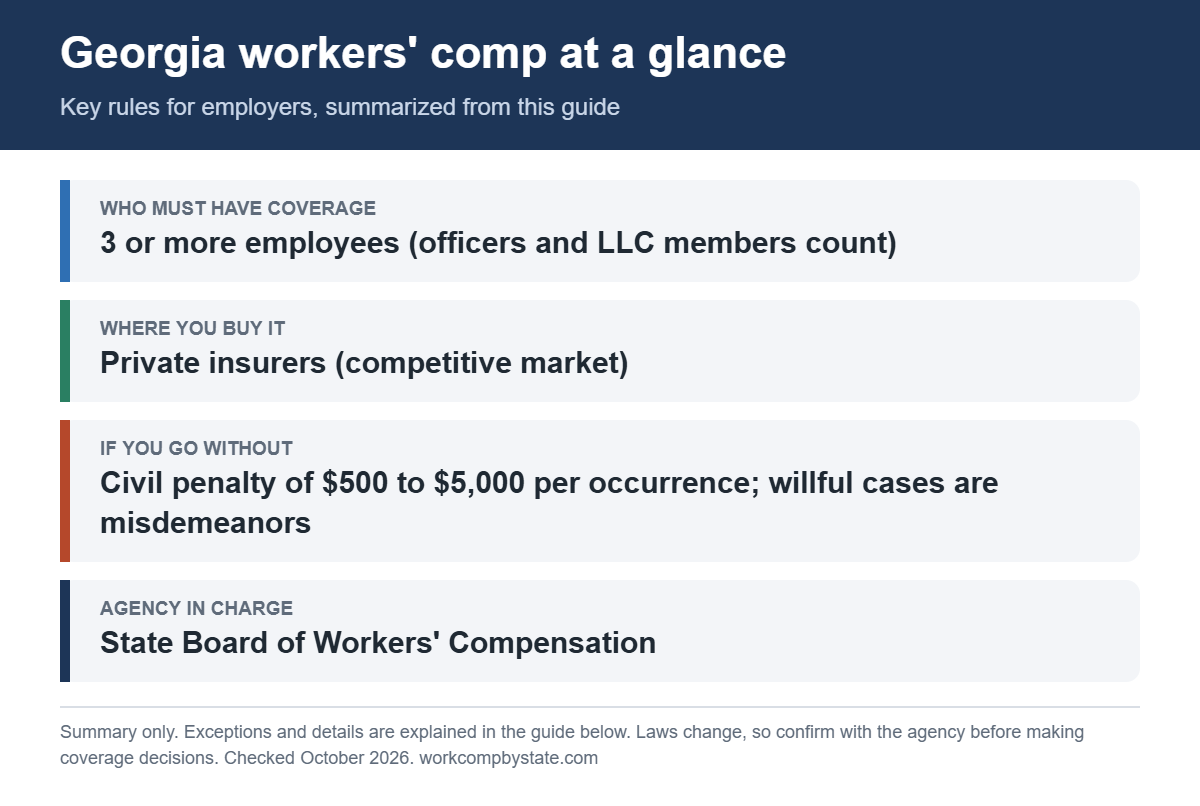
Georgia only requires workers’ comp once you “regularly” employ three or more people. That sounds generous, but the way Georgia counts catches many small companies off guard: corporate officers and LLC members count, part-timers count, and owners who exempt themselves still count. Here is how to do the count correctly, and what Georgia expects once you cross the line.
Step 1: Count the right people
The State Board of Workers’ Compensation (SBWC) says every employer “regularly employing three or more persons, part-time or full time” must carry coverage. Four details decide the count:
- Part-timers count if they work for you on a regular basis, for example someone who only works weekends.
- Seasonal staff can count if you regularly hire extra workers during a particular season.
- Corporate officers and LLC members count. If your business is a corporation or LLC, Georgia treats the officers or members as employees of the company.
- Exempt officers still count. Up to five officers or members can opt out of coverage for themselves, but the Board is clear that “officer exemptions do not reduce the number of employees” for the three-person test.
Sole proprietorships and partnerships work the other way around. Georgia treats sole proprietors and partners as employers, not employees, so they don’t count toward the three and aren’t covered unless they choose to be.
Three examples
| Business | Count | Coverage required? |
|---|---|---|
| Sole proprietor plumber with two full-time helpers | 2 (the owner doesn’t count) | No, but one more regular hire changes that |
| LLC with two members and one weekend employee | 3 (members count, regular part-timer counts) | Yes |
| Corporation with three officers who all filed exemptions, no other staff | 3 (exemptions don’t reduce the count) | Yes. The officers can exempt themselves, but the business is still subject to the Act |
Step 2: Decide who is covered
Officers and LLC members, up to five of them, can waive coverage for themselves by signing Form WC-10 and filing it with the insurance carrier. Sole proprietors and partners who want coverage for themselves use the same form to tell their carrier.
If you hire subcontractors, watch the coverage of their workers too. The SBWC notes that a contractor who sublets part of a job may be liable for the subcontractor’s employees if the subcontractor doesn’t have coverage. Collect a certificate of insurance before the work starts.
Step 3: Buy coverage
Georgia has no state fund. You buy a policy through an agent from a carrier licensed in Georgia. Businesses that can’t find coverage in the regular market can go to the Georgia Workers’ Compensation Assigned Risk Plan, which the National Council on Compensation Insurance (NCCI) administers. Self-insurance exists but is for large employers: it requires three years of audited financial statements, membership in the Georgia Self-Insurers Guaranty Trust Fund and security of at least $250,000.
Step 4: Post the right notices
Georgia is stricter about workplace postings than most states. In a conspicuous place you must post:
- a notice showing your insurance company’s name (or your certificate of self-insurance);
- the State Board’s Bill of Rights for injured workers;
- a Panel of Physicians, which is the list of doctors injured employees choose from. Georgia employers select a traditional panel or a managed care option.
The panel matters. If it isn’t posted properly, an injured worker may be free to choose their own doctor.
What it costs to ignore the law
- You still owe the benefits. An employer without required coverage is responsible for compensable injuries just as if it were insured.
- Extra charges on the claim. If you refuse or willfully neglect to insure, the Board can add attorney’s fees, civil penalties and a 10% increase in the compensation owed to the employee.
- A civil penalty of $500 to $5,000 per occurrence for violating the duty to provide coverage.
- A misdemeanor. Refusing or willfully neglecting to insure is punishable by a fine of $1,000 to $10,000, up to 12 months in jail, or both.
After an injury
As soon as you learn of an injury, file the Employer’s First Report of Injury (Form WC-1) with your insurer. If the injury causes seven or more days of lost time, it must be reported to the Board within 21 days of your knowledge of the disability. Late reports and late payments carry their own penalties. Our step-by-step guide to filing a workers’ comp claim walks through the whole process.
A way to lower the cost once you are covered
Georgia gives employers a direct discount for running a certified drug-free workplace. The State Board of Workers’ Compensation certifies the program, and certified employers receive a 7.5% reduction in their workers’ comp premium. The certification fee is $35. To keep the discount, you must send a copy of your certificate to your insurance carrier every year.
For a small contractor paying, say, $8,000 a year in premium (an illustrative figure), the credit is worth about $600 a year. The program has its own testing and policy requirements, so read the Board’s page before you apply.
Related guides
- Workers’ Comp for a One-Person LLC
- Do Part-Time Employees Need Workers’ Comp Coverage?
- What to Do When an Employee Gets Injured at Work
- Workers’ Comp Requirements by State: 50-State Comparison Table
Sources
- Georgia State Board of Workers’ Compensation: Employer Information
- Georgia State Board of Workers’ Compensation: Workers’ Compensation Insurance FAQs
- Georgia SBWC, drug-free workplace program
Last checked against the sources above on October 2, 2026. General information only, not legal or insurance advice.