
Workers’ Comp for Landscaping and Lawn Care Businesses
Lawn care looks simple from the street: a truck, a trailer, a couple of mowers and a crew. From a workers’ comp point of view it is one of the trickier small businesses to insure. Crews grow and shrink with the weather, the same workers may mow on Monday and take down a tree on Thursday, and many owners pay helpers in cash or on a 1099. Each of those habits can cost money at audit time or leave a business uninsured when someone gets hurt.
The easiest way to stay on top of it is to tie your insurance tasks to the calendar you already run on. Here is a year in the life of a small lawn and grounds company, and what to do with workers’ comp at each stage.
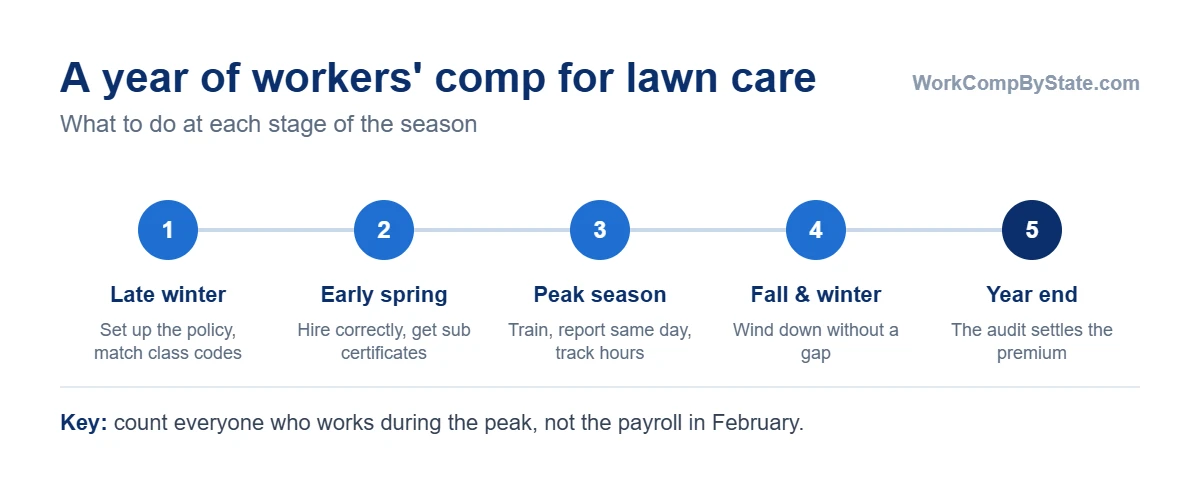
Late winter: set up the policy for the year ahead
Check whether you are required to carry coverage
Requirements depend on your state and your headcount. California requires coverage from the first employee. Others use thresholds: Wisconsin at 3 employees or $500 in wages in a quarter, North Carolina at 3, Florida at 4 outside construction, Tennessee and Missouri at 5 outside construction. Michigan’s rule catches small seasonal businesses in a specific way: coverage is required with 3 or more employees at one time, or with even 1 employee who works 35 hours a week or more for 13 weeks or longer in the prior 52 weeks. A single full-time mowing hand from April to July can cross that line.
| State | When a lawn care business needs coverage |
|---|---|
| California | From the first employee |
| Wisconsin | 3 employees, or $500 in wages in a quarter |
| North Carolina | 3 employees |
| Florida | 4 employees outside construction |
| Tennessee and Missouri | 5 employees outside construction |
| Michigan | 3 employees at one time, or 1 employee working 35+ hours a week for 13+ weeks in the prior 52 |
Count everyone who works for you during the peak, not the number on payroll in February. Tennessee and Wisconsin both count part-time workers, and Tennessee counts working family members. See the 50-state comparison table.
Match class codes to the work you actually do
Workers’ comp is priced per $100 of payroll by class code, and grounds work spans several codes. Mowing and routine maintenance, planting and bed work, tree trimming and removal, and hardscape installation are commonly rated differently, with tree work among the most expensive because of chainsaws, climbing and falling limbs. Tell your agent every service you plan to sell this year, including add-ons like snow plowing. If you only list “mowing” and later start removing trees, the audit will move that payroll to the higher code.
If you split payroll between codes, keep time records showing hours per type of work. Without them, a carrier may put all of a worker’s pay in the highest-rated code that worker performed.
In California, check your license
If you hold a California contractor’s license for tree work, note that the Contractors State License Board requires every active C-61/D-49 Tree Service licensee to carry workers’ comp whether or not they have employees. Other classifications have their own rules, so look up yours.
Early spring: hire the crew correctly
This is when most classification mistakes happen. A helper you pay by the day, who uses your mowers, follows your schedule and works your customer list, is very likely your employee no matter what the paperwork says. States test this in different ways:
- Tennessee uses a seven-factor test where control over the work matters most, and says a 1099 does not decide the question.
- Wisconsin requires an independent contractor to meet all nine parts of its test, including running a separate business, being responsible for operating expenses and being able to make a profit or suffer a loss.
- California presumes a worker is an employee unless the business proves the three parts of the ABC test.
A real subcontractor (for example, an irrigation company with its own trucks and other customers) is a different case. Before they start, get a certificate of insurance and verify it. In many states, if your sub’s workers are uninsured you can end up paying for their injuries. See construction subcontractor liability and certificates of insurance.
Peak season: keep the crew working and the records clean
- Train before the first cut. Mower rollovers on slopes, chainsaw kickback, heat and lifting are the injuries to plan for. OSHA’s heat guidance and equipment manuals are free starting points; see OSHA and workers’ comp.
- Report injuries the same day. Deadlines are short in many states. Indiana, for example, requires employers to report injuries needing more than first aid to their carrier within 7 days.
- Track hours by job type every week, not at year end.
- Update your agent when the crew grows far past your estimate. A small midyear adjustment beats a large audit bill.
Fall and winter: wind down without creating a gap
When the crew shrinks, it is tempting to cancel the policy. Think twice. Snow removal, leaf cleanup and equipment repair are still work, and a lapse can make restarting harder and pricier. If your state requires coverage only above a threshold, check the rules for leaving the system. In Tennessee, for instance, an employer that drops below five employees files Form I-3 to withdraw. In Wisconsin, an employer must keep coverage as long as it has any employees after becoming subject to the law, unless it meets the specific withdrawal conditions. See cancellation and lapse.
Year end: the audit
Your premium at the start of the year was an estimate. The audit replaces it with actual payroll by class code, plus any payments to uninsured subs.
An illustrative example. A three-truck lawn company estimated $150,000 of payroll, all under its maintenance code at a made-up rate of $5.00 per $100, for an estimated premium of $7,500. During the year it added tree removal and paid $30,000 of wages for that work, at an illustrative tree-work rate of $12.00 per $100. At audit, that $30,000 is moved from the maintenance code to the tree code. The premium rises by $30,000 / 100 x ($12.00 minus $5.00) = $2,100. If the owner had no time records to separate the work, the carrier could put even more payroll in the tree code. Real rates vary widely by state and carrier; these numbers only show the math. Read more in workers’ comp audits.
A business with big seasonal swings may prefer pay-as-you-go billing, which charges premium from actual payroll each pay period.
Related guides
- Seasonal and temporary workers
- 1099 workers and workers’ comp
- How workers’ comp premiums are calculated
- How to lower your premium
Sources
- MCL 418.115, Michigan employers covered
- Tennessee BWC, non-construction requirements and contractor test
- Wisconsin DWD, independent contractor test
- CSLB, workers’ compensation requirements for contractors
- Indiana Workers’ Compensation Board, compliance and injury reporting
- Wisconsin DWD, who must carry insurance
Last checked against the sources above on October 2, 2026.