
What Is an Experience Modification Rate (EMR), and How Do You Read Yours?
Your experience modification rate, often called the “mod” or “e-mod,” is a single number that moves your workers’ comp premium up or down based on your own claims history. A mod of 1.00 is average. Below 1.00 earns a credit. Above 1.00 adds a charge. For contractors it can also decide whether you are allowed to bid on a job at all.
This guide is built as a set of steps: what the number compares, which years go into it, why small businesses are treated differently, and what to check when your worksheet arrives.
Step 1: Know what the mod is comparing
The mod compares two things for your business:
- Expected losses: what a business in your class codes, with your payroll, would normally cost in claims. This comes from industry data collected by the rating organization. In most states that is NCCI; Tennessee’s Bureau of Workers’ Compensation, for example, names NCCI as its designated rate service organization. Some states run their own independent rating bureaus, and the monopolistic state funds run their own systems.
- Actual losses: what your claims really cost during the experience period, including money the carrier has set aside (reserves) for open claims.
If actual is lower than expected, your mod drops below 1.00. If it is higher, the mod rises. Washington’s Department of Labor and Industries puts it plainly in its own explanation: if a business’s claim costs are likely to be higher than others in its risk classes, it gets a factor greater than 1.
Step 2: Know which years are counted
A mod uses a few years of history, and it skips the most recent months on purpose. Claims take time to develop; a fresh injury’s final cost is not known for a while. Washington’s state fund, for example, uses three years ending 18 months before the rating year. Its rates that took effect January 1, 2019 used the period from July 1, 2014 to June 30, 2017. Other rating systems follow the same idea: several years of history, with the newest, least settled data left out.
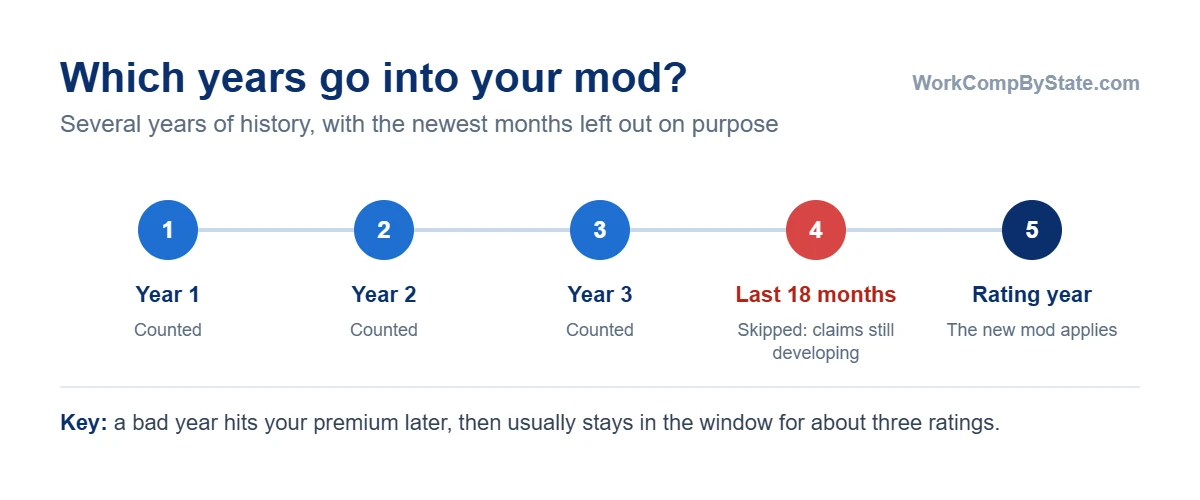
Two practical results:
- A bad year does not hit your premium right away. It shows up later.
- Once it shows up, it usually stays in the window for about three ratings before rolling off. Washington’s L&I notes that even ten claim-free years only count three at a time.
Step 3: Understand why size matters (credibility)
A tiny business with one bad claim has not proved much about its safety. A large business with hundreds of workers and a bad record has. Rating systems handle this with credibility, the weight given to your actual losses versus the expected losses. L&I defines it simply: the higher the credibility, the more your real losses count.
Two consequences for small businesses:
- Your mod stays closer to 1.00 in both directions. One claim will not send it to 1.60, but a great record will not push it to 0.60 either.
- Credibility is based on expected losses, not headcount. L&I points out that a business with many employees in low-hazard jobs still has low expected losses, so its clean record gets less weight than you might think.
Many states also do not rate a business at all until its premium reaches a minimum level. Those businesses sit at 1.00 by default. Washington is different: it applies experience rating whenever a business reported hours during the experience period.
Step 4: See why frequent small claims hurt more
NCCI’s formula splits each claim into a first portion counted at full value and an excess portion that is given much less weight. Five modest claims put five full first portions into the math. One large claim puts in one first portion and a heavily discounted remainder. That is why a pattern of small injuries often raises a mod more than a single serious one, and why safety programs that cut frequency pay off. The exact dollar split changes over time and by state, so ask your agent for the current figure in your state.
Step 5: Do the money math
The mod multiplies your premium before most discounts. Here is an illustrative example with made-up numbers for a small framing contractor whose manual premium (payroll times class rates, explained in how premiums are calculated) is $20,000:
- Wrong class codes or payroll. Payroll in the wrong class changes your expected losses.
- Stale reserves. If a claim closed for less than its reserve, ask the adjuster to update it before the next rating date.
- Claims that are not yours. A claim from another entity or a coding error should be removed.
- Missing periods. A gap can mean payroll was never reported to the bureau.
- Cut claim frequency: training, housekeeping, equipment checks.
- Report every injury quickly so care starts early and costs stay contained.
- Offer light duty when a doctor allows it. Washington’s L&I even encourages employers to keep paying injured workers’ wages to protect their claim-free status.
- Stay in touch with the adjuster on open claims and push for accurate reserves.
- How workers’ comp premiums are calculated
- Workers’ comp audits
- Workers’ comp for construction
- Workers’ comp glossary
- Washington L&I, experience rating
- Tennessee Bureau of Workers’ Compensation, how premium rates are set
| Mod | Premium on $20,000 manual premium | Compared with 1.00 | Over about three ratings |
|---|---|---|---|
| 0.85 | $17,000 | $3,000 less a year | About $9,000 saved |
| 1.00 | $20,000 | Average | |
| 1.25 | $25,000 | $5,000 more a year | About $15,000 extra |
Since a bad year can sit in the window for about three ratings, the 1.25 mod in this example could cost around $15,000 over three years on the same payroll. You can try different mods in our premium calculator.
Step 6: Check the worksheet line by line
Your mod comes with a rating worksheet that lists each policy period, payroll by class code, and every claim used. Ask your agent or carrier for it. Then look for:
Washington employers can get their calculation from their L&I account manager. In NCCI states, your agent or carrier can request it from the bureau.
Step 7: Know who looks at your mod besides your insurer
General contractors, property managers and some public agencies ask for your mod during prequalification, often wanting it at or below 1.00. A high mod can cost you work before price is even discussed. Keep a copy of your current rating letter with your certificate of insurance.
Step 8: Bring it down over time
More options are in how to lower your workers’ comp premium.
Related guides
Sources
Last checked against the sources above on October 2, 2026.