
Is Workers’ Comp Legally Required for Small Businesses?
In most of the United States, yes, once you have employees. But “most” hides a lot. The legal answer depends on your state, your industry, how your business is organized and who you count as an employee. A coffee shop with two employees needs a policy in Ohio but not in Georgia. A one-person roofing crew with a single helper needs one in Tennessee but would not in the same state if it sold furniture. This guide walks through the questions that decide it, in the order you should ask them.
Question 1: Does your state require coverage at all?
Forty-eight states require private employers to carry workers’ comp once they reach the state’s trigger. Two do not. Texas lets employers opt out and become “nonsubscribers.” South Dakota’s labor department states that no law requires any employer there to carry it, while warning that uninsured employers can be sued in civil court.
If you are in Texas or South Dakota, the question becomes whether to carry it, not whether you must. Our Texas nonsubscriber guide covers what opting out exposes you to.
Question 2: Where is your state’s trigger?
Most states require coverage from the first employee, part-time included. The rest set a higher bar or use a different measure. A few examples from states we cover in depth:
- Part-time workers. They count almost everywhere. Tennessee’s Bureau of Workers’ Compensation says part-timers, minors and working family members are all included in the count.
- Corporate officers. Georgia and North Carolina count officers toward the threshold, even if they are excluded from the policy.
- Family members. Missouri counts family members within the third degree of relationship.
- Owners. Sole proprietors, partners and LLC members usually do not count and are usually not required to cover themselves. Tennessee construction is a major exception.
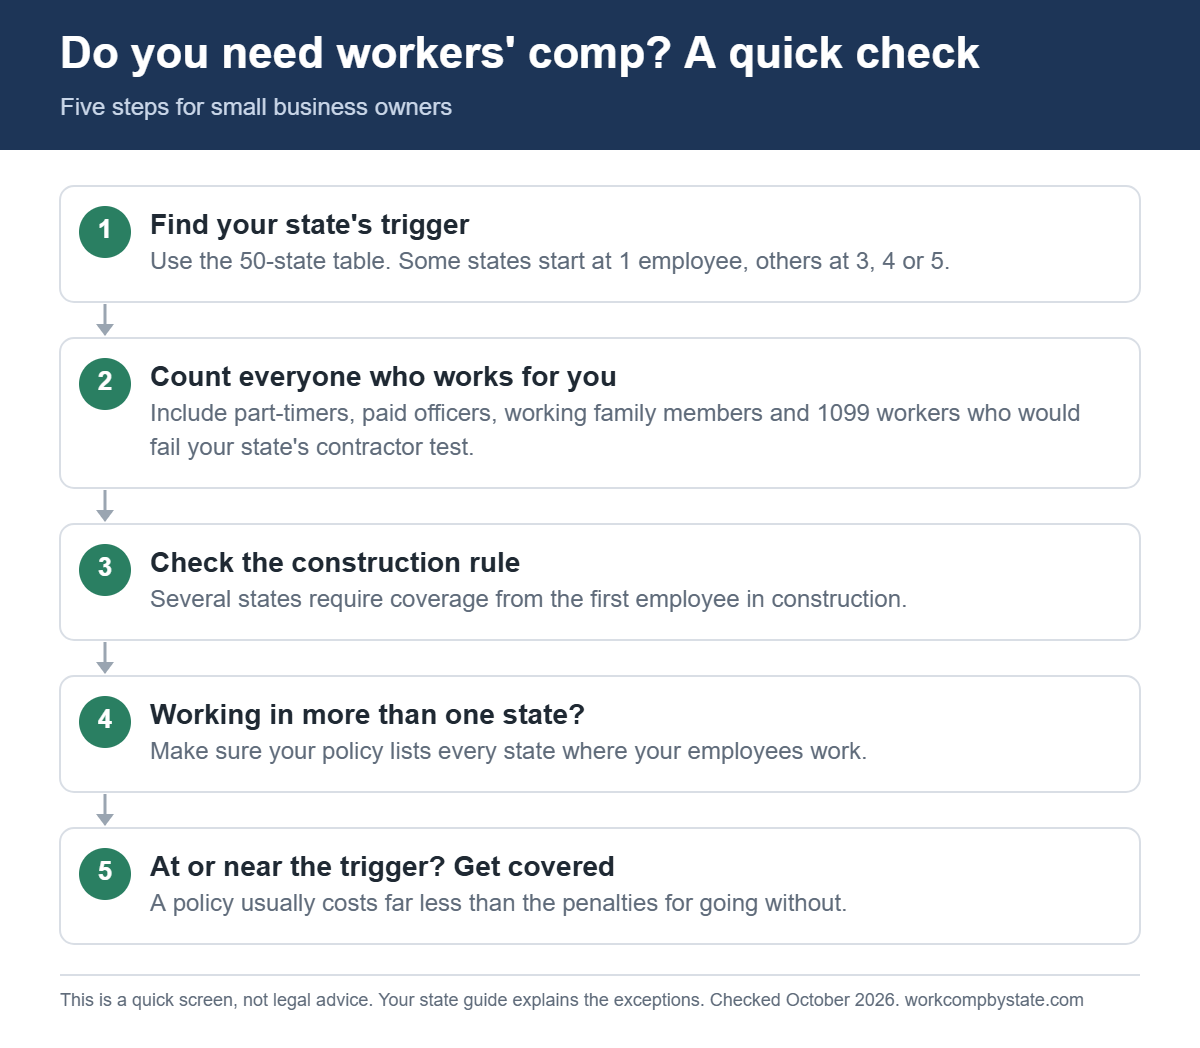
- Find your state’s trigger in the 50-state table.
- Count everyone who works for you, including part-timers, paid officers, working family members and anyone paid on a 1099 who would fail your state’s contractor test.
- If you are in construction, use your state’s construction rule.
- If you are at or near the trigger, get coverage. The cost of a policy is small next to the penalties.
- What is workers’ compensation insurance and how does it work?
- Workers’ comp exemptions: who doesn’t need coverage
- Part-time employees and workers’ comp
- Penalties for not carrying workers’ comp by state
- South Dakota Department of Labor and Regulation
- Tennessee Bureau of Workers’ Compensation, non-construction requirements
- RSMo 287.030, Missouri employer definition
- MCL 418.115, Michigan employers subject to the Act
- Wisconsin DWD, insurance requirements
- Massachusetts DIA, insurance requirements
| Trigger | States (examples) |
|---|---|
| First employee, part-time included | Most states |
| Three employees | Georgia, North Carolina, Virginia |
| Four employees | Florida, outside construction |
| Five employees | Missouri and Tennessee, outside construction |
| Hours or wages instead of headcount | Michigan: one employee at 35 hours a week for 13 weeks. Wisconsin: $500 in wages in a quarter |
| No requirement | Texas (nonsubscribers) and South Dakota |
Our 50-state comparison lists the trigger for every state.
Question 3: Are you in construction?
Construction is the most common exception to a higher threshold. Florida, Missouri and Tennessee all require coverage at one employee for construction businesses. Tennessee also expects construction business owners to cover themselves unless they obtain an exemption. If you build, remodel, roof or repair, check your state’s construction rule before anything else.
Question 4: Who counts as an employee?
This is where most small businesses get the answer wrong. States differ on:
Question 5: Are your “contractors” really contractors?
A business with two employees and three 1099 workers may actually have five employees in the eyes of the state. Each state applies its own test, and none of them treats a 1099 as decisive. Wisconsin requires a contractor to meet nine separate conditions. Colorado presumes a worker is an employee unless two conditions are met. Tennessee weighs seven factors, with control of the work counting most. See our guide to workers’ comp and 1099 workers for how to document a real contractor relationship.
Question 6: Do you work in more than one state?
Each state where your employees work can apply its own rules. Your policy must list those states. Massachusetts, for example, requires out-of-state employers whose policies list it only in the “all states” section to have their carrier file proof that Massachusetts coverage is provided. Washington, Ohio, North Dakota and Wyoming sell coverage only through their state funds, so a private multistate policy will not work there.
A quick way to decide
Example
A family bakery in Missouri has the owner, her husband and her nephew on payroll, plus two weekend counter staff. That is five employees, because Missouri counts family members. The same bakery in Georgia, organized as an LLC with the owner as the only member, would count four employees and also need coverage there, because Georgia’s trigger is three. In Tennessee, the same five people would also reach that state’s five-employee line, because Tennessee counts part-timers and working family members.
What happens if you are required and do not have it
Penalties vary widely, from per-day fines to stop-work orders and criminal charges. Missouri can charge up to three times the annual premium or $50,000, whichever is greater. Massachusetts can close a business the same day. And in every state, an injury during an uninsured period is paid by the business itself. Our penalties by state page compares 20 states in detail.
Frequently asked questions
I am the only person in my business. Do I need workers’ comp?
Usually not, because most states do not require owners to cover themselves. Construction is the main exception in some states, and many clients will still ask for a certificate before hiring you. See our one-person LLC guide.
Do I need coverage for a part-time employee?
In most states, yes. Part-time workers count toward thresholds and must be covered once you are required to carry a policy.
If I am below my state’s threshold, should I buy coverage anyway?
Many small businesses do. Without it, an injured employee may be able to sue you directly, and clients and landlords often require proof of coverage.
Related guides
Sources
Last checked against the sources above and the linked state guides on October 2, 2026.